
Assets abroad, foreign accounts, foreign income: the scenarios are many and often intertwined.
Not to mention the origin of foreign assets and funds, an often thorny issue to which the French tax authorities (administration fiscale) are increasingly attentive: An inheritance? A gift? Foreign income? Were they declared?
And there is no shortage of tax questions:
Is the inheritance taxable in France, and what about a gift?
Do I have to pay tax when I sell a property abroad?
And what about my foreign income: is it taxable in France? Even if I have already been taxed abroad?
And the IFI (the new ISF, which targets real estate only): are my foreign properties affected?
Do I have to declare my foreign bank accounts ? And my life insurance policies? And my savings? And what about my trading account?
Our Tax Guide is here to answer all the questions you may have, in the most practical way possible.
Foreign Accounts: What to Do?
First of all, it is important to remember that holding bank accounts abroad is, in principle, not illegal. Except in cases of proven tax fraud, holding bank accounts abroad is perfectly legal. The only obligation on the individual is to declare their foreign accounts every year.
From a tax perspective, it is therefore simply a matter of declaring them every year, using form 3916 / 3916-bis.
This declaration must be made again every year, and for each account.
Even if you have already declared your account in the past, you will need to do so again every year.
When you close the account, you will have to declare its closure the following year, using the same form 3916 / 3916-bis. In subsequent years, you will no longer have to declare this account.
The reporting obligation is very broad. It covers all types of accounts held abroad: current account, savings account, securities account, capitalisation account, life insurance, trading account…
Questions and Answers
I declared my foreign account last year; do I need to do it again this year?
Yes, the declaration must be made again every year, for as long as the account exists.
I have closed my account; do I still have to make a declaration?
Yes, you will have to make the declaration again, indicating the date on which the account was closed.
An account closed in 2022 must be declared in 2023. However, in 2024 and subsequent years, no further declaration will be required for this account.
I forgot to declare my account. I opened it a long time ago. What will happen if I regularise my situation?
In the event of regularisation, fines will in principle be applied. The limitation period for fines is 5 years. In other words, the tax authorities are entitled to apply fines for a maximum of 5 years.
The amount of the fine depends on the country concerned. Generally, it is €1,500 per year and per account, but it can rise to €10,000 in certain cases.
I have an account abroad and I do not wish to declare it. What are the risks?
First of all, since the declaration of accounts is an obligation, it is advisable to comply with this obligation.
If the individual chooses not to comply with this obligation, the likelihood of being “detected” by the tax authorities depends on the country concerned. There are automatic exchanges of banking data with many countries around the world. Foreign banks send banking information to the French tax authorities, every year. The likelihood of being “detected” is therefore increasingly high.
If the concealment of the foreign account is part of tax fraud, the consequences can be severe, both from a tax and a criminal standpoint: 80% surcharges, fines, criminal prosecution.
If the concealment is not part of tax fraud, there will in principle only be tax consequences: 80% surcharges, which may sometimes, depending on the case, be reduced to 40%, and fines.
If I want to regularise, how do I go about it? What are the benefits?
Regularisation takes the form of filing a file with the tax authorities.
This file will include, in particular:
- A written statement on the origin of the funds, and documents substantiating this origin
- The bank documents for the entire regularised period
- A statement of assets for the regularised period
- The amended returns for income tax and any amended ISF / IFI returns
This is generally a long and tedious file to put together.
In addition, the tax authorities remain entitled to apply fines and surcharges (which they do, although the surcharges may, depending on the case, be reduced)
I have received a letter from the tax authorities asking me to regularise my foreign accounts. What should I do?
Naturally, respond to this request.
If you have received this type of letter, it is very likely that your foreign assets are substantial.
The stakes are therefore high, and the potential tax reassessments could also be very significant.
It therefore seems advisable to seek the assistance of a tax lawyer who routinely handles the regularisation of foreign accounts, and who will be able to help you avoid many pitfalls, secure the procedure and, depending on the case, reduce the reassessments.
If you decide to respond to the request on your own, which is entirely possible, here are some key points to watch:
- The origin of the funds: always tell the truth, but be careful how you phrase it. The devil is in the details, and, in these cases, a detail can have serious consequences
- The filing of amended returns for income tax and ISF / IFI: very often, you are entitled to numerous tax credits, not to mention the various mechanisms that allow you to benefit from tax reductions, so you must claim them all and not miss out on these opportunities for tax reductions
Foreign Income: What to Do?
Every tax resident of France is in principle required to declare all of their income every year, whether that income comes from France or from abroad.
Foreign income can be of several types:
- Rents from properties located abroad
- Financial income (interest, dividends or capital gains) from investments abroad
- Professional income: this may be salaries, or income from a business activity abroad
In principle, all this income is taxable in France, as long as the person receiving it is a tax resident of France.
HOWEVER, there are many tax treaties, with many countries, which may derogate from this rule of taxation in France.
In most cases, tax treaties will provide for the following derogating rules:
- Foreign rents : taxable abroad, but must still be declared in France. The rents will, however, be exempt or may benefit from a tax credit in France
- Financial income: taxable in France, but with a tax credit in France taking into account the tax paid abroad
- Professional income: very different scenarios, and therefore very different solutions depending on the case. It will sometimes be taxable in France, sometimes not.
In all cases, the tax treaty, where one exists, will need to be read.
As for the forms to be used, this will be form 2047, and sometimes other types of forms, such as the 2042 C.
Form 2047 will make it possible to declare foreign income and, where applicable, to claim the tax credit in France.
The fields of the 2047 must be carried over to other returns: mainly the 2042, and sometimes other forms. When filing online, automatic carry-over can be activated, but be careful not to “overwrite” boxes of the 2042 that are already pre-filled. It is therefore generally preferable to carry over the amounts manually, without activating automatic carry-over.
Form 2047 contains the various sections needed to declare foreign income.
It also contains sections allowing you to claim tax credits in France for the taxes you have already paid abroad, in order to avoid, or at least limit, double taxation.
Great care must be taken when completing these forms, as errors could cause you to miss out on tax reductions to which you may be entitled.
These forms nevertheless remain far from intuitive for those who are not used to them.
If the stakes are high for you, do not hesitate to seek the assistance of a tax lawyer, who will prepare your returns accurately.
Sale of a Property Abroad: Do I Have to Pay Tax in France?
As a tax resident of France, the sale of a property abroad, if it has generated a capital gain, must in principle be declared in France.
However, France has signed international tax treaties with many States.
It is therefore necessary to refer to the tax treaty, where one exists, to determine how the gain is taxed in France.
If, after reviewing the tax treaty, the capital gain is taxable in France, form 2048-IMM must be filed.
Be careful, the deadline is very short: one month from the date of the deed of sale.
The difficulty with sales of properties abroad lies in two aspects:
- The complex legal aspects: is the sale taxable in France? And if so, am I entitled to a tax credit? Each tax treaty contains different details. Yet the devil is in the details, and from one treaty to another, the consequences can be enormous: some treaties will result in taxation, others will not
- The file to be put together is relatively substantial: form 2048-IMM, a cover letter explaining the context, copies of the purchase and sale deeds, documents evidencing the taxes paid abroad, etc.…
Property Abroad: Do I Have to Pay IFI?
First of all, remember that owning real estate abroad is, in principle, not illegal.
Moreover, there is no specific reporting obligation for properties abroad, except where the taxpayer is liable to IFI (real estate wealth tax, impôt sur la fortune immobilière).
Consequently, in the absence of liability to IFI, the property does not, in principle, have to be declared.
Liability to IFI is triggered as soon as the tax household owns, on 1st January of the year, net real estate assets exceeding 1.3 million euros.
Each property must be valued at its market value (the value at which it could be sold) on 1st January of the year.
All properties are in principle taken into account: flats, houses, land, offices, SCIs (property holding companies), SCPIs (real estate investment trusts), the portion of life insurance policies relating to real estate, etc.…
Furthermore, both French and foreign properties are taken into account.
There are, of course, exceptions, in particular where the property is used for professional purposes by the tax household (subject to certain strict conditions).
There are also possible allowances, in particular for the main residence (a 30% allowance on the value of the property) and for rented properties (no precisely fixed rate, but a customary discount of 10% on the value).
Inheritance of Foreign Assets from a Deceased Person Who Was a Foreign Tax Resident: Am I Taxed in France? How Do I Declare It?
Please note: only the most common case is dealt with here: you are a tax resident of France, the deceased was a tax resident abroad, and the assets transferred are located abroad (the other scenarios are not covered here: deceased resident in France with foreign assets / assets in France of a foreign deceased, etc. …)
A relative of yours has died abroad, was a tax resident abroad, and owned assets there, all or part of which have passed to you?
The first thing to understand is that, as a tax resident of France, any inheritance, even a foreign one, is in principle taxable in France.
There are, however, two major exceptions to this principle:
- At the time of the succession, you were indeed a tax resident of France, but you had not been one for at least 6 years during the ten years preceding the death
- A tax treaty on inheritances exists and provides that foreign assets are not taxable in France
Case 1: You are a tax resident of France and have been one for at least 6 years during the ten years preceding the death. In addition, there is no tax treaty on inheritances with the country concerned
The inheritance is therefore in principle taxable in France. The tax paid abroad on assets located abroad will, however, be creditable against the tax due in France.
Example: you inherit a house abroad worth €200,000. Abroad, €8,000 of inheritance tax is paid. In France, €35,000 is due (by assumption). You will only pay €27,000 (€35,000 – €8,000) to the French tax authorities.
Please note that certain forms must be filed: in particular, form 2740-SD.
Form 2740 SD
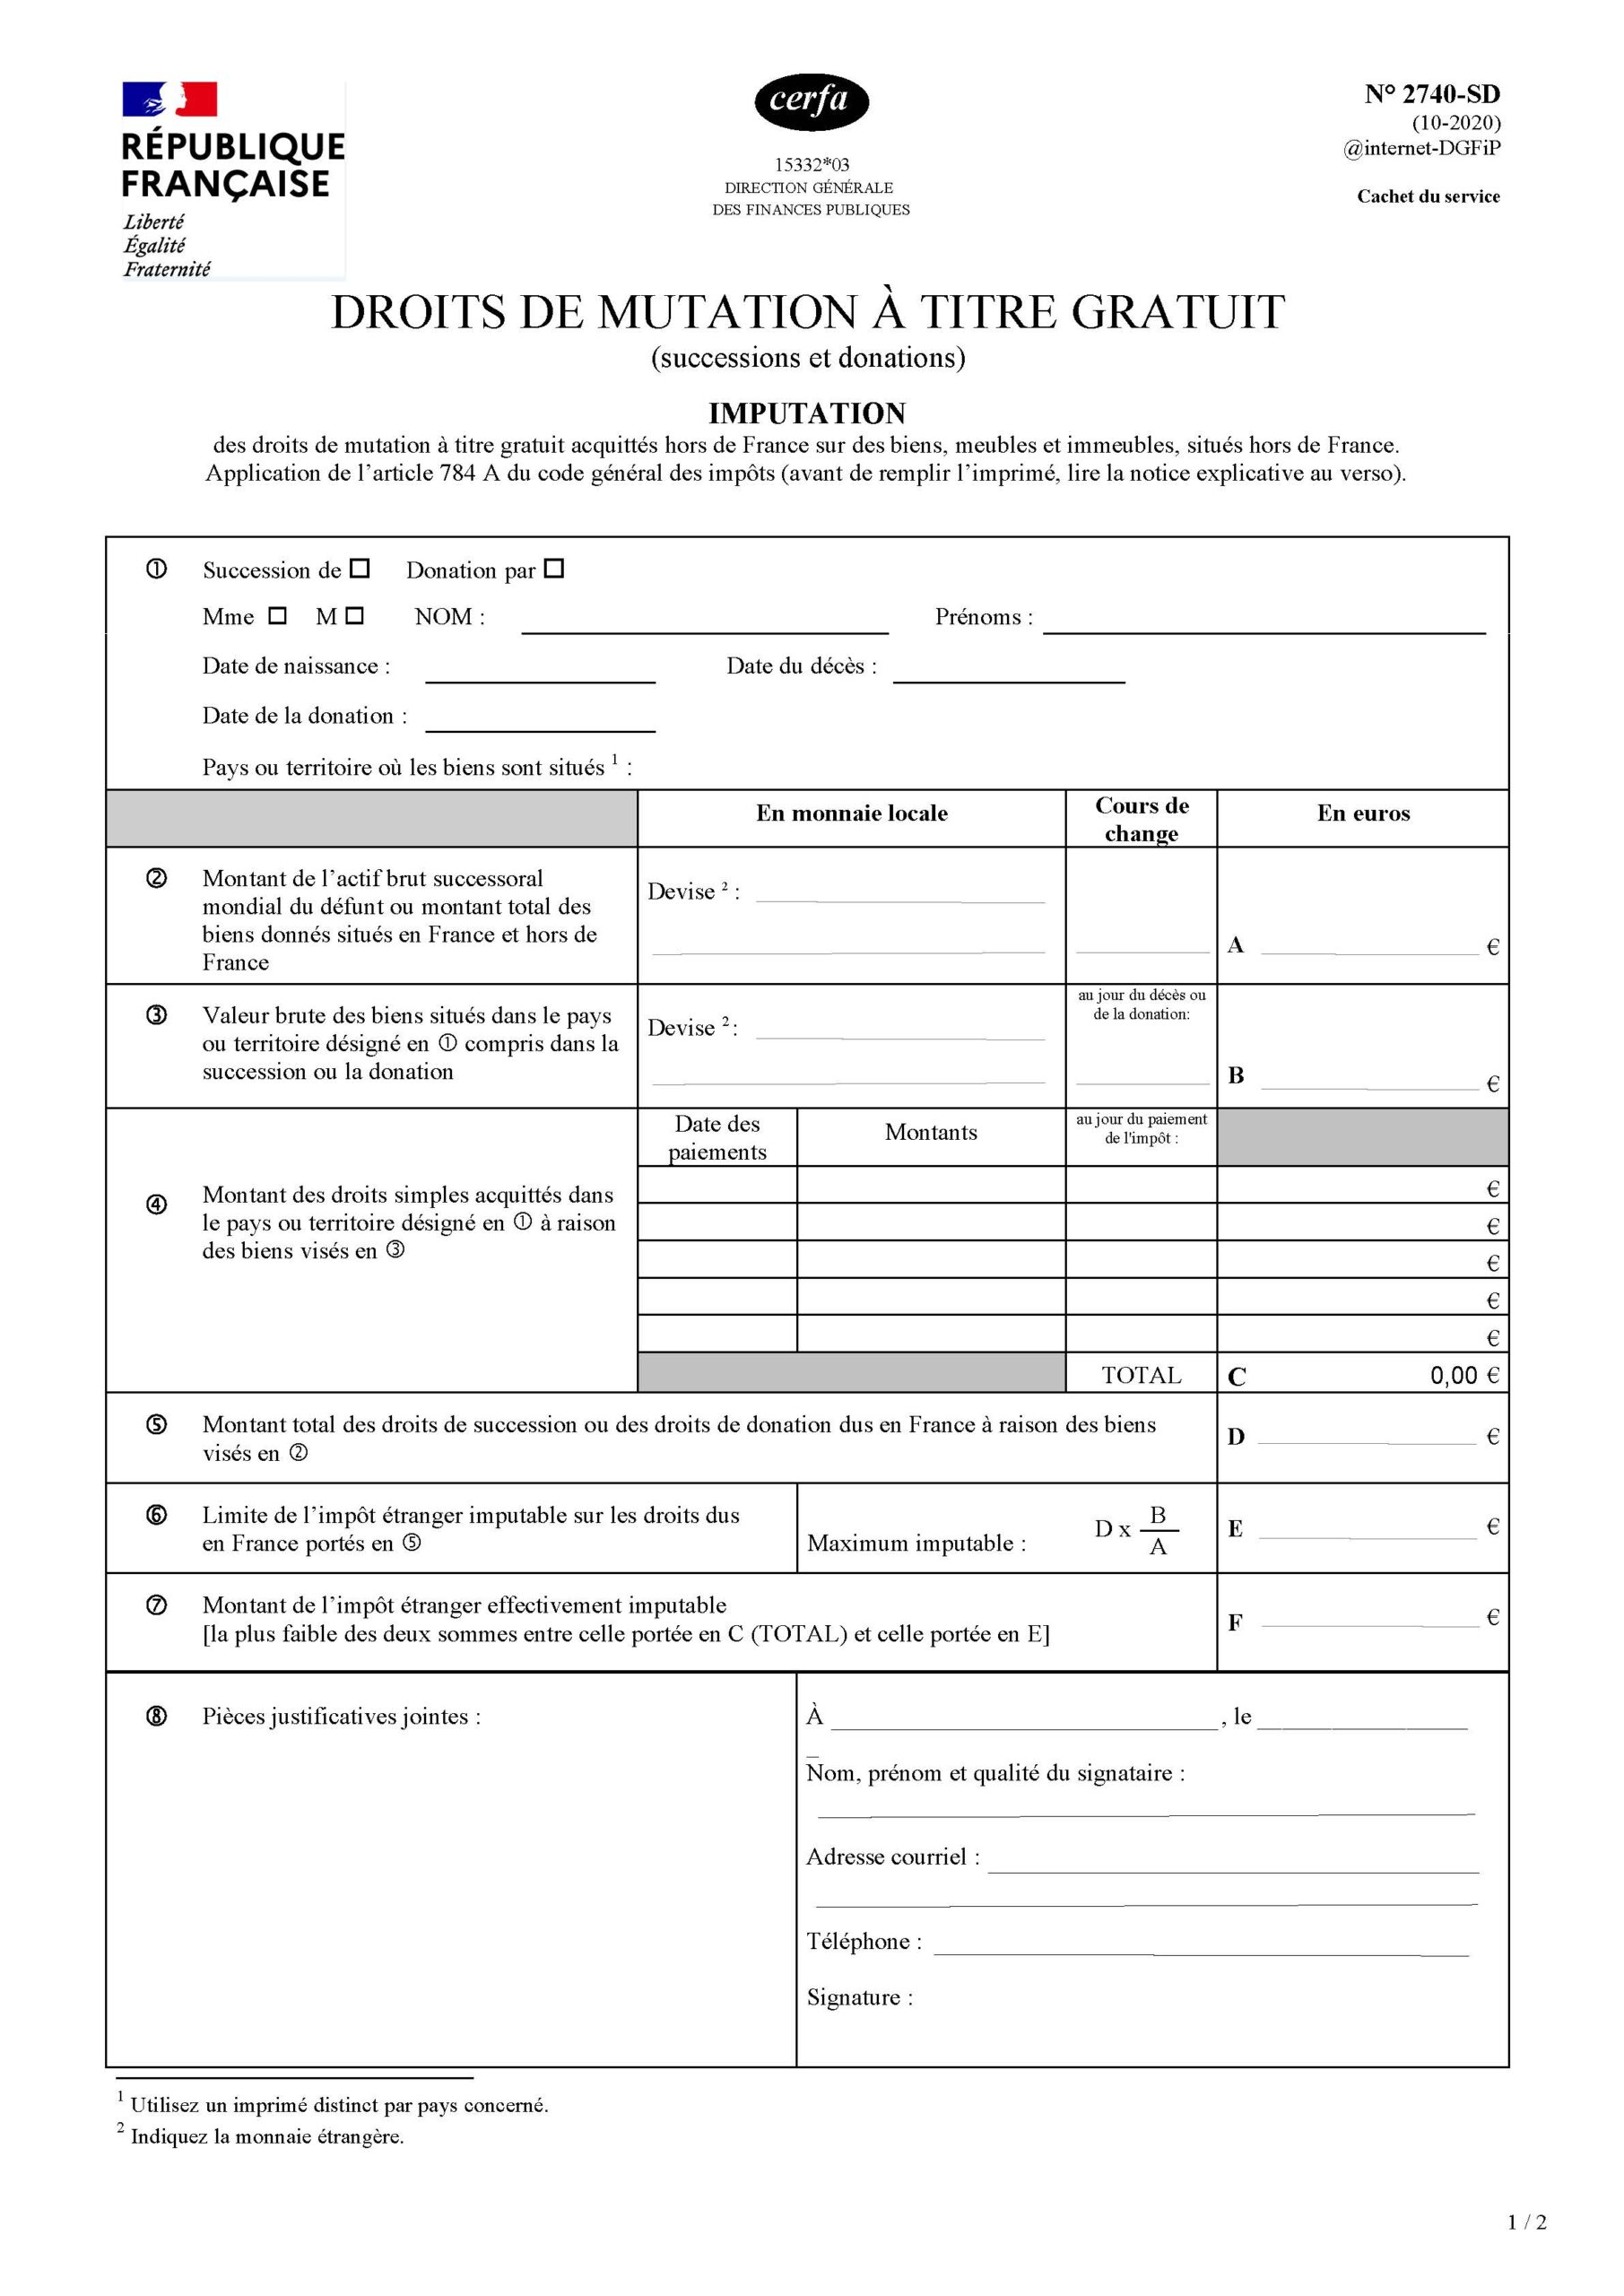
It is through this form that you can, if the conditions are met, claim the credit for foreign tax and thus reduce the tax payable in France.
The other forms to be completed are the 2705 SD and 2705 S SD and, where applicable, the 2705 A SD in the case of life insurance.
Form 2705-S-SD (extract)
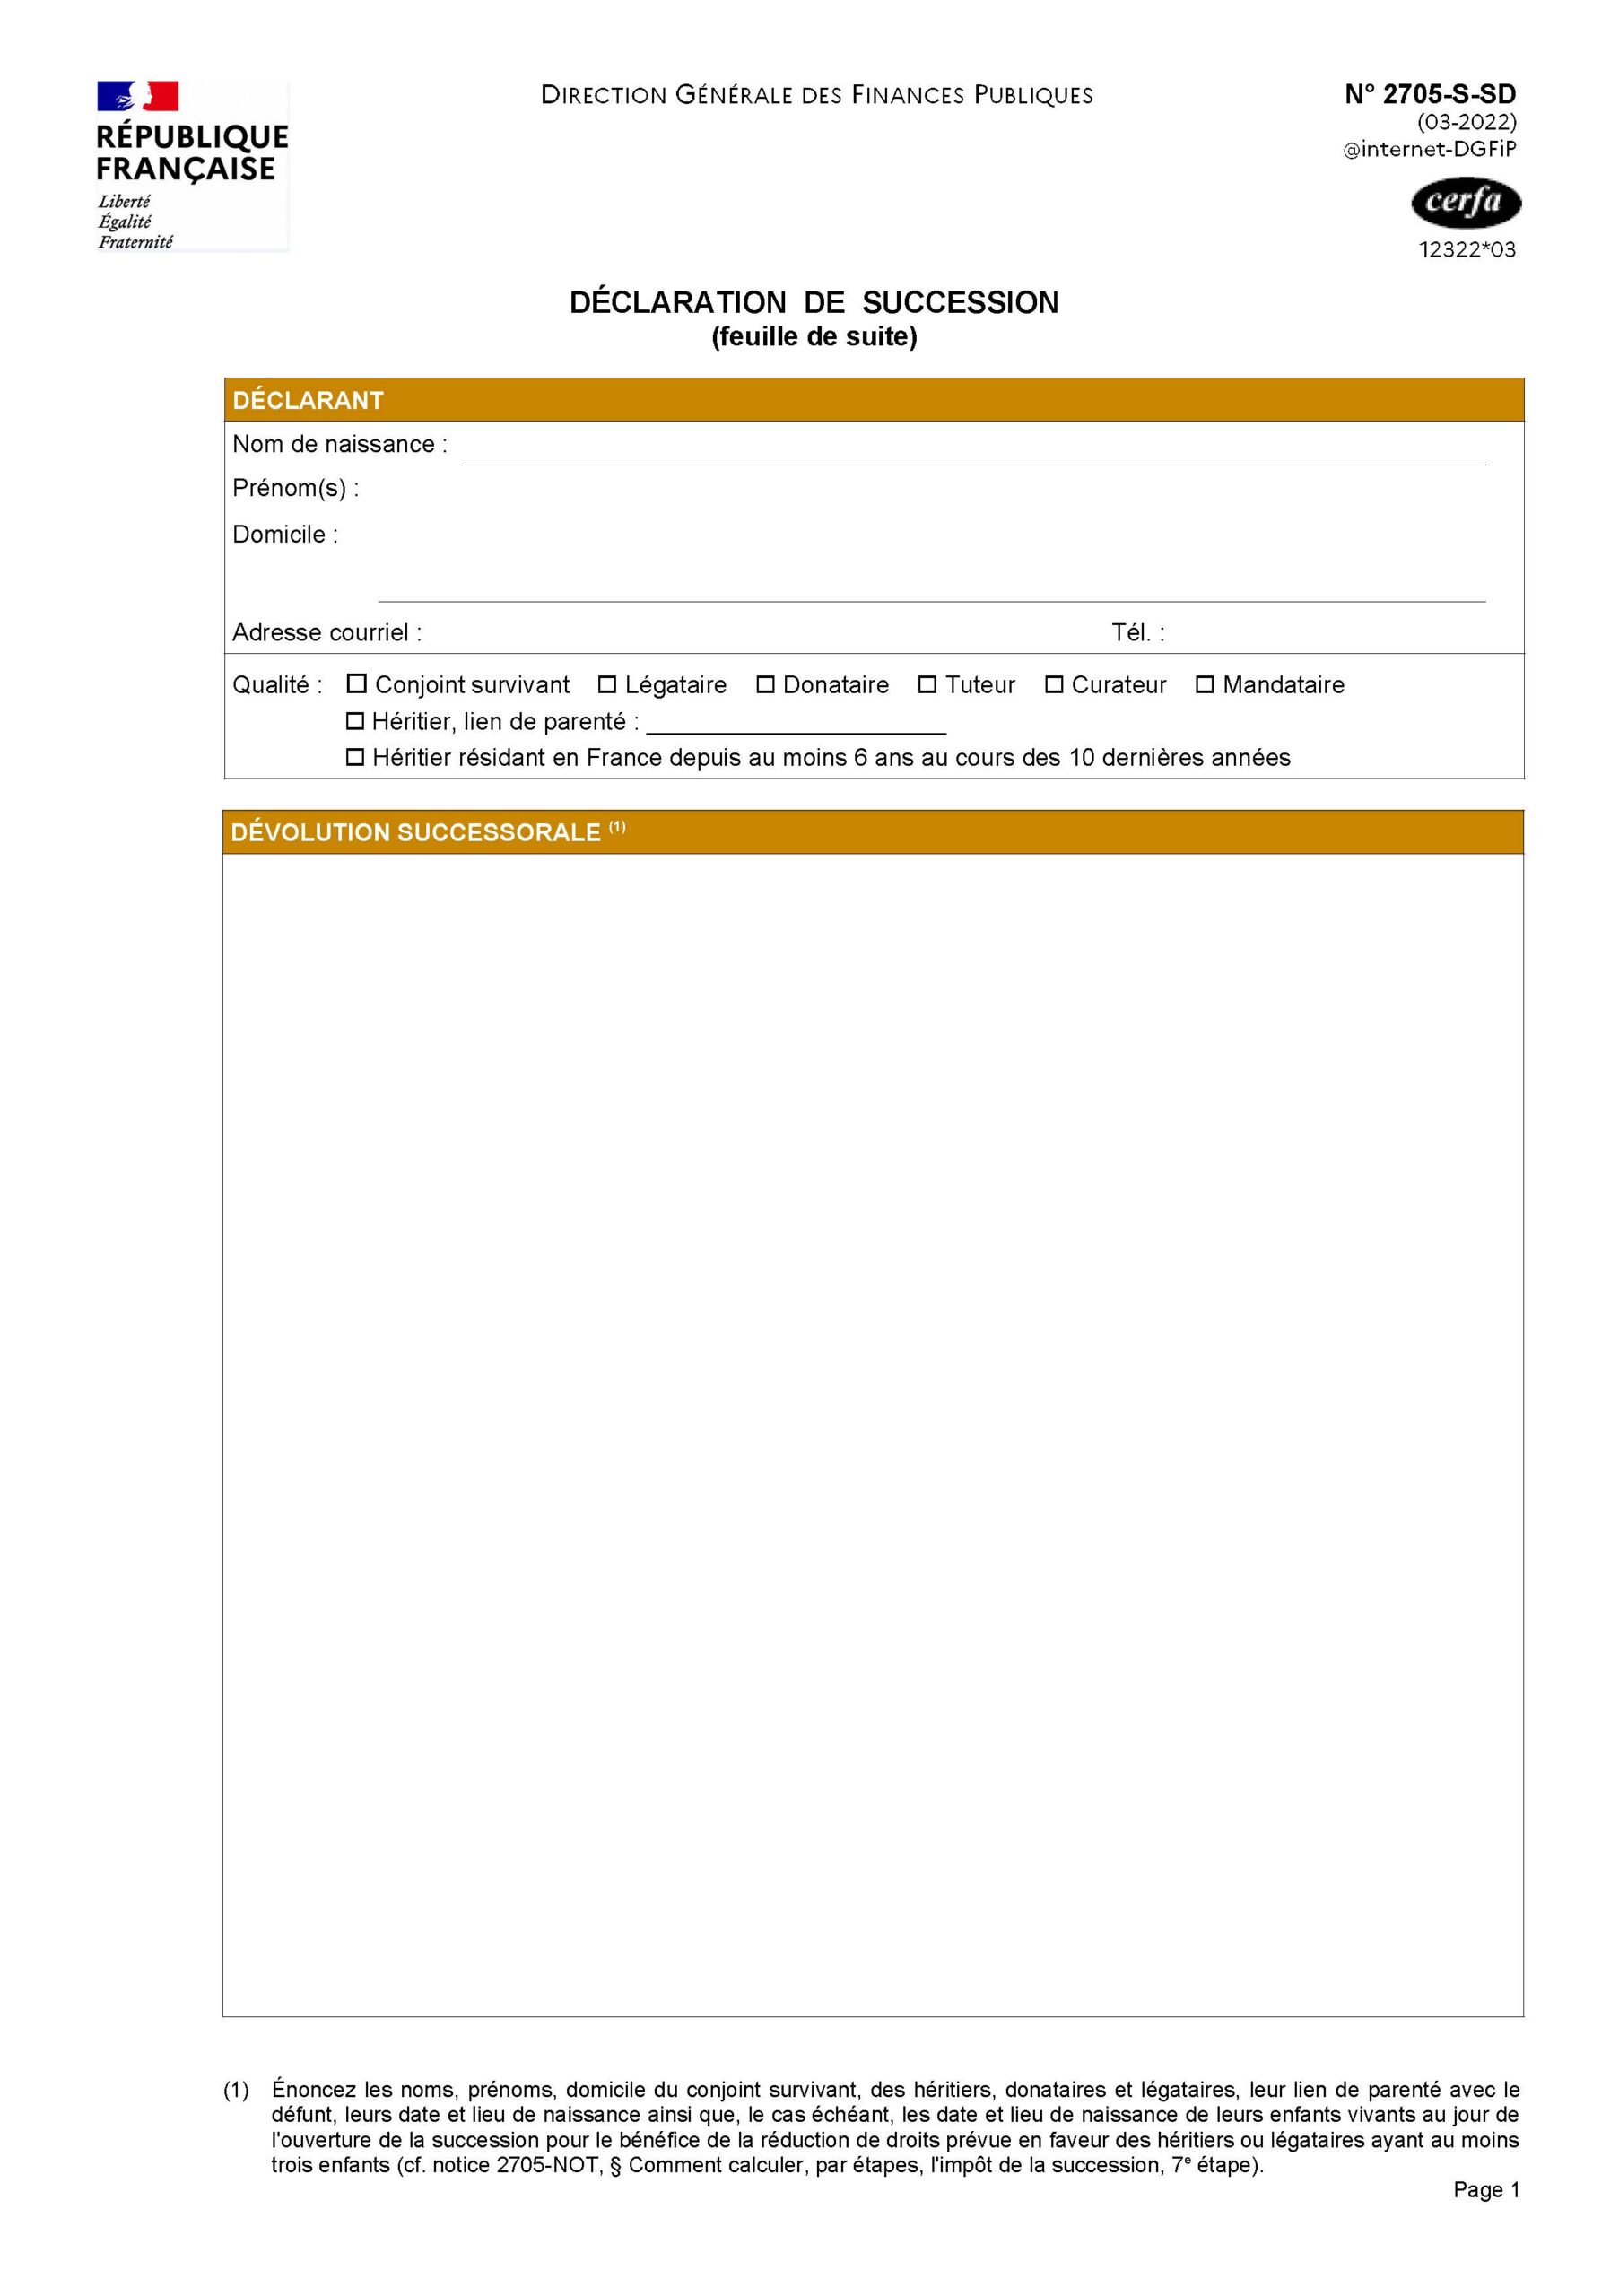
Be careful, these forms must be completed rigorously. They will have a very direct impact on the inheritance tax due in France.
Case 2: You are a tax resident of France but have not been one for at least 6 years during the ten years preceding the death
Since the deceased was a foreign tax resident and the assets are located abroad, no inheritance tax is in principle due in France.
Case 3: You are a tax resident of France and have been one for at least 6 years during the ten years preceding the death, but there is a tax treaty on inheritances with the country concerned
In this case, the treaty will need to be analysed to determine how it allocates taxing rights between the two States.
Some treaties will make it possible to eliminate French taxation completely, others only partially, and others still will not allow French taxation to be eliminated at all.
The treaty must therefore be read carefully in light of your specific situation.
If the stakes are high for you, the assistance of a tax lawyer seems highly advisable.







0 Comments